Table of Contents
If you have been saving for a new-build home but still feel the deposit or mortgage required is a little out of reach, the Help to Buy Wales 2026-27 scheme could be the answer. The Welsh Government has extended the scheme, and eligible applications can now be submitted until 31st March 2027. But how does it work, who can apply, and what should you consider before going ahead? Let’s take a closer look.
What is Help to Buy Wales 2026-27?
Help to Buy Wales 2026-27 is a Welsh Government scheme designed to assist eligible buyers purchase a new-build home from a participating builder.
Under the scheme:
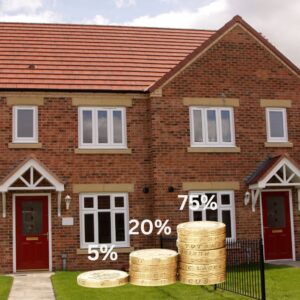
- You provide a deposit of at least 5% of the property’s purchase price.
- The Welsh Government provides an equity mortgage of up to 20%.
- You arrange a repayment mortgage to cover the remaining amount.
- The property must cost no more than £300,000.
- Your application must be submitted by 31 March 2027.
It is very important to understand that the government contribution is an equity mortgage, not a discount or a grant. This means it will eventually need to be repaid, and the amount you repay can change according to the future value of your home. You can read the current official overview on the Welsh Government’s Help to Buy – Wales page.
What Has Changed with the Help to Buy Wales 2026-27 Extension?
The most important news is that the Help to Buy Wales 2026-27 scheme gives eligible buyers more time to apply. Applications can now be submitted up to and including 31st March 2027, subject to the rules and availability. This is great news for buyers who thought they had missed their opportunity. The extension may provide valuable extra time to save a deposit, explore new-build developments, and prepare a mortgage application.
However, the extension does not mean that every property or every buyer will qualify. The home must be eligible, the builder must participate in the scheme, and you will still need to pass the affordability and credit checks required by your chosen mortgage lender.
We always recommend checking the latest Help to Buy – Wales eligibility criteria before making financial commitments or paying a reservation fee. Or talk to us, our contact details are at the end of this article.
How Does Help to Buy Wales 2026-27 Work in Practice?
It’s a great question. We think this straightforward example may be the easiest way for us to explain the scheme.
Imagine you are buying an eligible new-build for £200,000:
| Source of funding | Amount | Percentage |
|---|---|---|
| Your cash deposit | £10,000 | 5% |
| Welsh Government equity mortgage | £40,000 | 20% |
| Your repayment mortgage | £150,000 | 75% |
| Total purchase price | £200,000 | 100% |
Without the equity mortgage, a buyer with a £10,000 deposit might need to borrow £190,000 from a mortgage lender. With Help to Buy Wales 2026-27, the required mortgage, in this example, is reduced to £150,000. This, therefore, could make the mortgage more affordable. It may also give you access to a different selection of mortgage products because your main mortgage represents a smaller proportion of the property’s purchase price.
However, approval is never automatic. Your mortgage lender will still follow the strict assessment protocols, reviewing your income, regular spending, existing credit commitments, credit history, and overall ability to maintain the repayments.
Who is Eligible for Help to Buy Wales 2026-27?
To qualify under the current rules for the Help to Buy Wales 2026-27 scheme you must meet a number of conditions. these include:
- Buying an eligible new-build property in Wales.
- Purchasing from a builder registered with the scheme.
- Paying no more than £300,000 for the property.
- Funding at least 80% of the purchase price through your deposit and a repayment mortgage.
- Providing a deposit of at least 5%.
- Taking out a first-charge repayment mortgage with a qualifying lender.
- Using the property as your main home.
- Not buying the property as an investment or buy-to-let.
- Not renting out your existing home while using the scheme to purchase a second property.
Is the Help to Buy Wales 2026-27 scheme exclusively for first-time buyers? It’s a common question, but the current Welsh Government eligibility page does not state that applicants must be first-time buyers. Eligible home movers may therefore also be able to apply, provided they meet the full criteria and the property will be their only residence.
Every buyer’s situation is different, so it is worth checking your eligibility with us before assuming that you do or do-not qualify.
Does the Property Have to be a New Build?
Yes. Help to Buy Wales 2026-27 is available for eligible new-build properties purchased from participating builders. You can find the current list of builders on Help to Buy Wales 2026-27: participating builders | GOV.WALES
You cannot normally use the scheme to buy an older property from an existing owner. Additionally, homes sold through the scheme must also achieve a minimum Energy Performance Certificate (EPC) rating of B. This energy efficiency requirement may help buyers benefit from a home that is more efficient to run, although actual energy costs will depend on the property and how it is used.
Before reserving a home, ask the developer to confirm in writing that:
- It is registered with Help to Buy – Wales.
- The individual property is eligible.
- The purchase price is within the £300,000 limit.
- The home will meet the required EPC standard.
How Much Deposit Will I Need for the Help to Buy Wales 2026-27 Scheme?
You will need a minimum deposit equal to at least 5% of the full property price. For example:
| Purchase price | Minimum 5% deposit | Maximum 20% equity mortgage | Remaining 75% mortgage |
|---|---|---|---|
| £180,000 | £9,000 | £36,000 | £135,000 |
| £220,000 | £11,000 | £44,000 | £165,000 |
| £250,000 | £12,500 | £50,000 | £187,500 |
| £300,000 | £15,000 | £60,000 | £225,000 |
These examples assume that you use the maximum 20% equity mortgage from the Welsh Government scheme. Your actual arrangement may be different. Also, you must be able to fund at least 80% of the purchase price through your deposit and repayments mortgage combined.
Remember that your deposit is not the only upfront expense. You may also need money for legal work, mortgage fees, surveys, moving costs, insurance, and any applicable Land Transaction Tax. Don’t panic though, we will go through all of this with you when you get in touch.
When Do I Have to Repay the Equity Mortgage Back on the Help to Buy Wales 2026-27 scheme?
The equity mortgage provided through Help to Buy Wales 2026-27 must be repaid within 25 years, although you can repay some or all of it earlier. The amount owed is linked to percentage of your home’s market value rather than the remaining fixed at the original cash amount.
Let’s say the Welsh Government provides £40,000 towards a £200,000 home. That represents 20% of its value. If the property is later worth £250,000 when the equity mortgage is repaid, you would need to pay back £50,000, which is 20% of the property’s current value. Of course, the same principle can work in the other direction. If the home’s value falls, the amount corresponding to the government’s percentage may also fall, subject tot he terms of your agreement.
This shared exposure to changes in the market value of your property is one of the most important parts of the scheme to understand. A smaller repayment mortgage today should be balanced against the future cost of repaying the equity mortgage. The Welsh Government explains the rules in more detail in its guidance on repaying your Help to Buy Wales 2026-27 equity mortgage here.
How do I Pay Part of the Equity Mortgage Early?
You can pay part of the equity mortgage early before the end of the 25 year term, with or without selling your property. If you make a partial payment, the balance remaining under the equity mortgage must represent at least 5 % of the property’s current market value. You will also need an independent valuation from a qualified valuer from the Royal Institution of Chartered Surveyors.
There may be valuation, legal, and administration costs to pay. It is therefore sensible to consider your long-term repayment plan before applying for the Help to Buy Wales 2026-27 scheme, rather than waiting until you are ready to sell or remortgage.
Don’t worry. We can help you explore how your main mortgage and equity mortgage may work together over the years ahead.
Can I Sell or Remortgage a Help to Buy Wales 2026-27 Home?
Yes, but there are additional steps involved. When you sell the property, the equity mortgage will normally need to be repaid based on the relevant percentage of its current market value. An independent valuation may be required as part of the process. You may also be able to remortgage, but permission is required and the new lender must meet the scheme’s requirements. If you want to borrow more money, this is generally restricted unless the additional borrowing is being used to repay some or all of the equity mortgage.
This all means that future mortgage planning can be more involved than it would be with a standard purchase. Speaking to a broker, like ourselves, who understand the scheme, could save you time and help you avoid unexpected complications.
Can I Rent Out or Make Changes to the Property?
Your Help to Buy property must be your main residence (as outlined earlier in the article). It is not intended for buy-to-let investment, and you cannot ordinarily sublet the whole property.
In exceptional circumstances subletting may be considered, but you must obtain the required permission. The Welsh Government’s current guidance indicates that you may be able to rent out a room while continuing to live in the property yourself.
Whilst you are responsible for maintaining the property, you may need permission before making non-cosmetic or structural alterations. Approval for significant improvements is generally considered only in particular circumstances, such as adaptations required because of a disability.
How Do I Apply for Help to Buy Wales 2026-27
The exact journey can vary, but it will generally include the following steps:
- Check your finances. Review your income, spending, deposit and credit commitments.
- Speak to a mortgage adviser. Establish how much you may be able to borrow and whether the scheme appears suitable for you.
- Find an eligible new-build property. Confirm that the builder is registered and that the home meets the current price and energy-efficiency rules.
- Reserve the property. Read the reservation terms carefully and understand which payments are refundable.
- Choose a trained conveyancer. Buyers using the scheme must instruct a conveyancer who has completed the relevant Help to Buy – Wales training.
- Arrange your repayment mortgage. The mortgage must be with a qualifying lender and meet the scheme’s requirements.
- Complete the application form. Your completed Help to Buy – Wales application must be submitted with the required information.
Is Help to Buy Wales 2026-27 the Right Choice for Me?
Another great question! For some buyers, Help to Buy Wales 2026-27 may provide a realistic path towards a new-build home with a smaller deposit and a lower initial repayment mortgage. However, it will not be right for everyone.
Before deciding please consider:
- Whether you prefer a new-build home.
- Whether suitable properties are available within the £300,000 cap.
- What your monthly mortgage payments will be.
- How you may eventually repay the equity mortgage.
- What could happen if the property increases in value.
- The fees and restrictions attached to the scheme.
- Whether a standard mortgage or another homeownership option could suit you better.
That’s why it always advisable to talk with a mortgage broker like us. We’ll ensure you do not only focus on whether you can buy the property. We’ll also explore whether the mortgage, household builds, maintenance, and other costs will remain comfortable if your circumstances change.
How Else Can Harbour Mortgage Solutions Help?
We understand that buying a new home can feel exciting, emotional, and, let’s be honest, a little overwhelming! Added to this, an equity mortgage has it’s own rules, so it is perfectly normal to have lots of questions. At Harbour Mortgage Solutions, our friendly, independent mortgage advisers can:
- Review your income, deposit and existing commitments.
- Explain how the scheme could apply to your circumstances.
- Assess how much you may be able to borrow.
- Search for an appropriate mortgage from qualifying lenders.
- Explain the mortgage fees and costs clearly.
- Help you prepare your application.
- Support you from your first enquiry through to completion.
We are based in Barry, more fondly known as Barrybados! We help buyers across South Wales and throughout the UK. Our advice is always personal and tailored to your individual needs and long-term goals, plus we will stay with you every step of the way, on hand to answer any future questions that may arise, because we truly care about our clients.
What Should I do Next about the Help to Buy Wales 2026-27 Scheme?
If Help to Buy Wales 2026-27 sound as though it could help you make your next move, start by checking your budget and speaking to one of our experienced mortgage advisers. It is far better to understand fully you potential mortgage options before falling in love with a particular property or paying a reservation fee.
Remember, the current application deadline is 31st March 2027, but buying a home and arranging the necessary mortgage, legal work, and scheme approval can take time. Start early. Contact Harbour mortgage Solutions for friendly, straightforward mortgage advice tailored to your personal circumstances.
Scheme rules, deadlines and eligibility requirements can change. The information in this article is a general guide and does not constitute personalised financial or legal advice. Please check the latest Welsh Government guidance before making a decision.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up with repayments on a mortgage or any other debt secured on it.